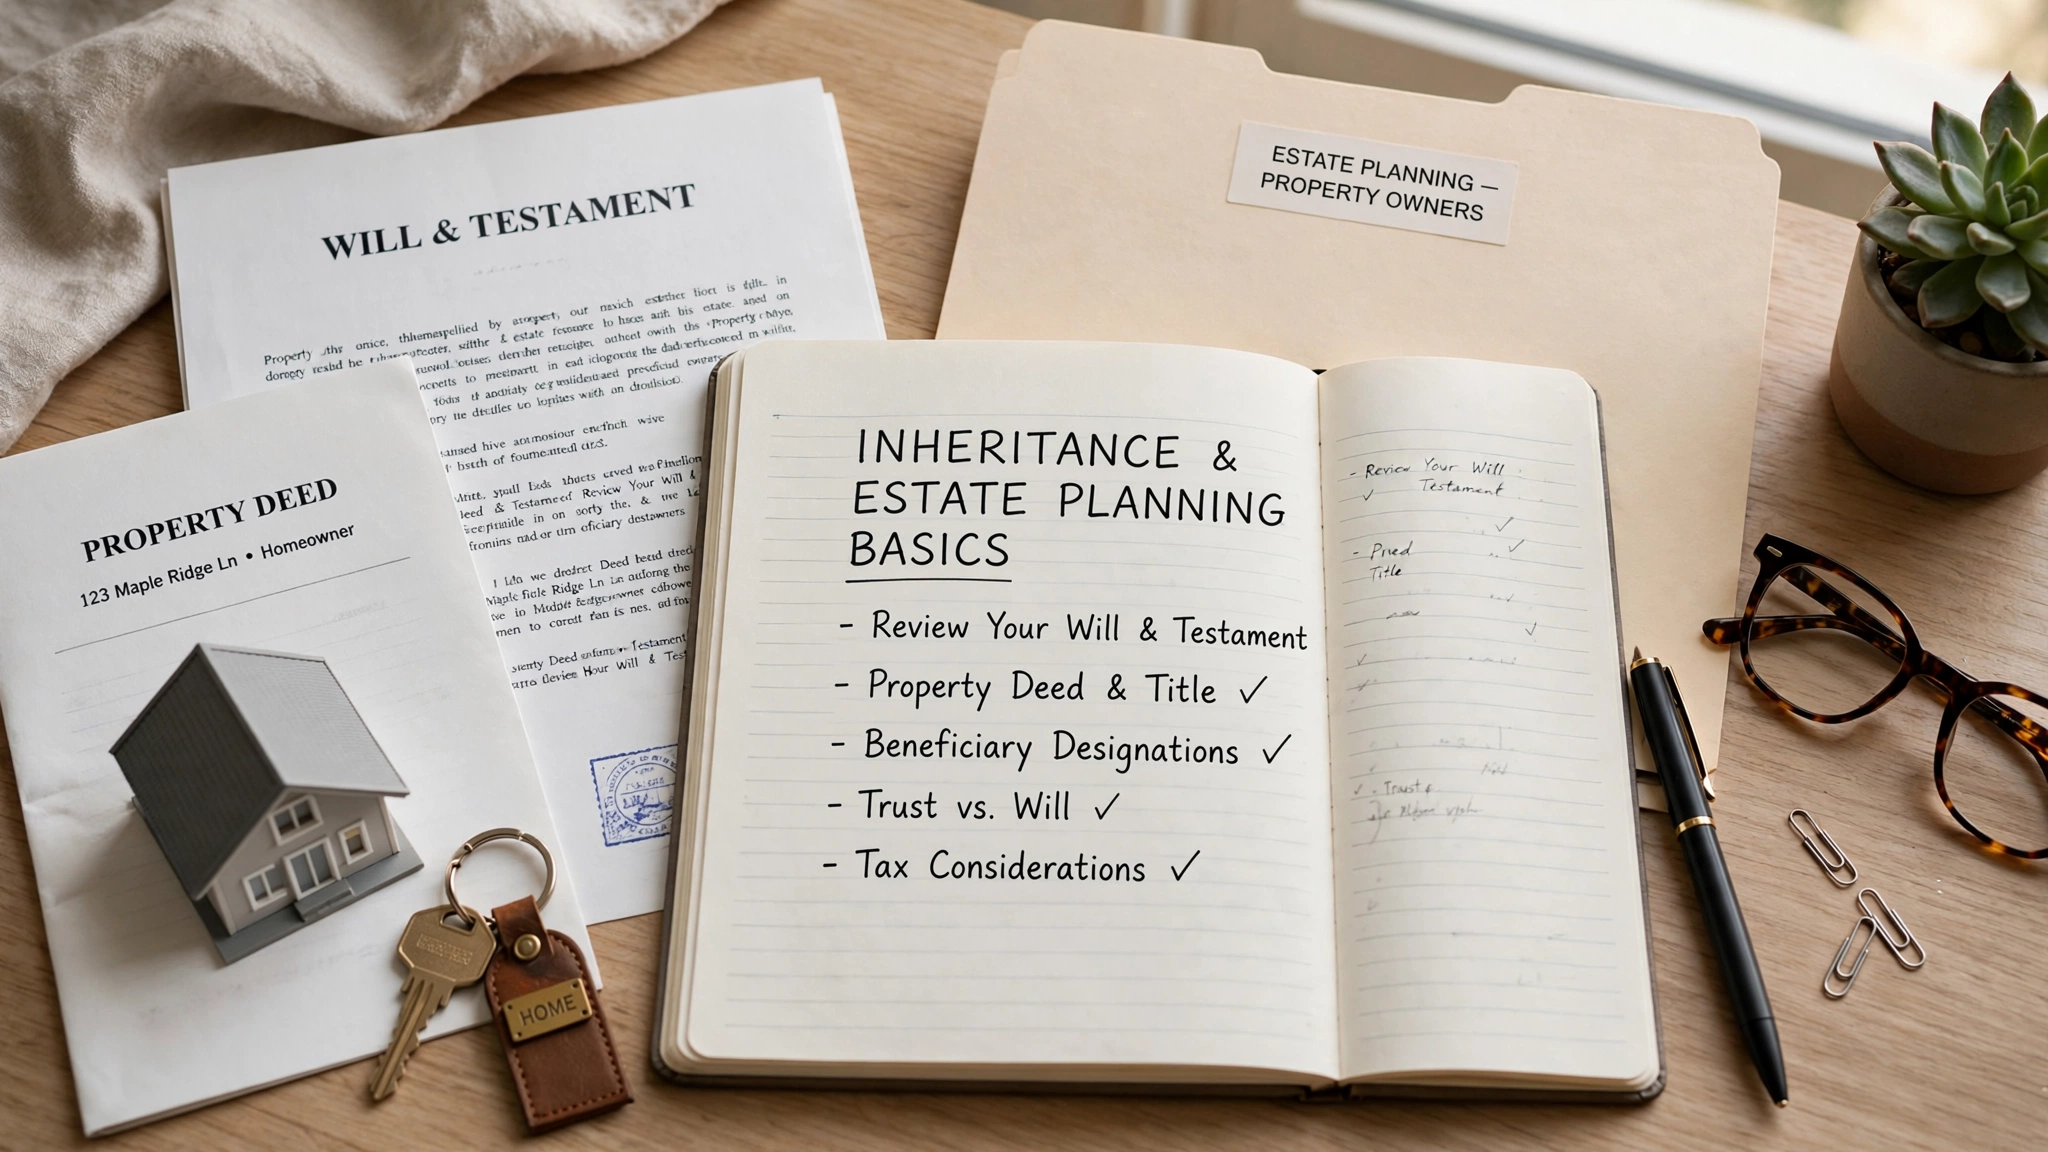
Have you ever considered what will happen to your hard-earned property and assets once you’re no longer around to manage them? The thought of inheritance and estate planning can be daunting, especially for property owners, as it involves ensuring that your loved ones are taken care of and your legacy is preserved. Without proper planning, the distribution of your estate can lead to family conflicts, legal battles, and financial uncertainties. This is a common problem faced by many individuals who own properties but haven’t delved into the intricacies of estate planning.
Now, imagine the emotional turmoil and stress your family members could experience if you were to pass away suddenly without a clear estate plan in place. Disputes over property ownership, confusion regarding your wishes, and delays in asset distribution can strain relationships and create a chaotic aftermath during an already challenging time. The lack of a well-thought-out inheritance plan can not only jeopardize your legacy but also burden your loved ones with unnecessary legal complexities and financial burdens.
The good news is that understanding the basics of inheritance and estate planning can empower you to take control of your assets and ensure a smooth transfer of wealth to the next generation. By familiarizing yourself with key strategies, legal tools, and considerations for property owners, you can proactively safeguard your legacy and provide your family with clarity and security for the future. Get ready to explore the essential principles of inheritance planning and unlock the secrets to preserving your property assets for generations to come.
Importance of Estate Planning for Property Owners
Estate planning is crucial for property owners to ensure that their assets are distributed according to their wishes after their passing. Without a proper estate plan in place, there can be a significant risk of disputes among family members and loved ones regarding the distribution of property. By creating a comprehensive estate plan, property owners can protect their assets and provide clarity on how they want their estate to be managed.
Benefit of Asset Protection
One of the key benefits of estate planning for property owners is asset protection. Through estate planning strategies such as creating trusts and establishing a will, property owners can safeguard their assets from potential creditors and legal claims. This protection ensures that their hard-earned assets are preserved for their intended beneficiaries, providing peace of mind and financial security for future generations.
Key Terms in Estate Planning
Estate planning involves the process of anticipating and arranging for the disposal of an individual’s estate during their life. It typically aims to minimize potential taxes and distribute assets to beneficiaries as per the individual’s wishes. Will is a legal document that outlines how a person’s assets should be distributed upon their death. Trust is a legal arrangement in which a person (the trustor) gives control of their property to a trustee for the benefit of beneficiaries. Probate is the legal process through which a deceased person’s will is proved valid, and their assets are distributed under court supervision.
Power of Attorney
Power of attorney is a legal document that grants someone the authority to act on behalf of another person in legal or financial matters. It can be general, giving broad powers, or limited, specifying certain actions or timeframes. Durable power of attorney remains in effect even if the individual becomes incapacitated. Having a power of attorney in place is crucial for estate planning to ensure that decisions can be made in case of illness or incapacity.
Steps to Create an Estate Plan
Creating an estate plan is essential for individuals looking to ensure their assets are distributed according to their wishes after they pass away. The first step in creating an estate plan is to take inventory of all your assets, including properties, investments, bank accounts, and personal belongings. Next, you will need to designate beneficiaries for each asset, specifying who will inherit each item. It is also crucial to appoint an executor who will be responsible for managing your estate and ensuring your wishes are carried out.
Another important step in creating an estate plan is to establish a power of attorney, granting someone the authority to make financial or medical decisions on your behalf if you become incapacitated. Additionally, drafting a will or trust is vital to outline how your assets should be distributed and to minimize potential conflicts among your heirs. Regularly reviewing and updating your estate plan is recommended, especially after major life events such as marriage, divorce, or the birth of children.
Tax Implications of Inheritance for Property Owners
Property owners need to be aware of the tax implications associated with inheritance to effectively plan for the transfer of assets to their heirs. Inheritance tax is a tax imposed on the value of assets inherited by individuals after the original owner passes away. Depending on the jurisdiction, inheritance tax rates and exemptions can vary, so it is crucial to understand the specific laws in your area.
Property owners can take steps to minimize inheritance tax liabilities by utilizing strategies such as gifting assets during their lifetime, establishing trusts, or setting up life insurance policies. Seeking guidance from a financial advisor or tax professional can help property owners navigate the complex tax implications of inheritance and develop a comprehensive estate plan that maximizes the value of their assets for future generations.
5. Common Mistakes to Avoid in Estate Planning
Not Updating Your Estate Plan: One common mistake in estate planning is failing to update your plan regularly. Life circumstances change, such as marriages, divorces, births, deaths, and financial situations. Failing to review and update your estate plan can lead to unintended consequences and discrepancies.
Not Considering Tax Implications: Another mistake is not considering the tax implications of your estate plan. Failure to account for taxes can result in a significant portion of your estate going towards taxes instead of your intended beneficiaries. It’s essential to work with a financial advisor or tax professional to ensure your estate plan is tax-efficient.
6. Tax Implications of Inheritance for Property Owners
When property owners inherit assets, there are various tax implications to consider. Inheritance taxes may apply depending on the value of the assets and the relationship between the deceased and the heir. Understanding these tax implications can help property owners plan their estate effectively to minimize tax liabilities.
Additionally, capital gains taxes may come into play when inheriting property. The cost basis of the inherited property could impact the amount of capital gains taxes owed when the property is sold. Property owners should be aware of these tax implications to make informed decisions about their estate planning strategies.
6. Tax Implications of Inheritance for Property Owners
Tax implications of inheritance can significantly impact property owners. Inheritance tax is a tax on property or money that individuals inherit from someone who has passed away. In some regions, there may be exemptions or thresholds for inheritance tax, but it’s crucial for property owners to understand how it applies to their situation. Additionally, capital gains tax may come into play if inherited assets are later sold for a profit. Proper estate planning can help minimize the tax burden on beneficiaries by utilizing strategies such as trusts or gifting assets during one’s lifetime.
Understanding Capital Gains Tax
Capital gains tax is a tax on the profit made from the sale of an asset, such as real estate or stocks. When property owners inherit assets, they may face capital gains tax when they sell those assets in the future. The tax implications can vary based on the value of the asset at the time of inheritance and the selling price. Property owners should be aware of the potential capital gains tax liabilities and consider consulting with tax professionals or financial advisors to develop a tax-efficient estate plan that takes into account these implications.
Resources for Further Estate Planning Information
When it comes to estate planning, it’s crucial to have access to reliable resources for guidance and information. Fortunately, there are numerous resources available to help individuals navigate the complexities of estate planning. One valuable resource is seeking advice from estate planning attorneys who specialize in this area of law. These professionals can provide personalized guidance based on your unique circumstances and goals.
Additionally, there are online resources such as government websites, legal forums, and educational materials that offer valuable insights into estate planning. Websites like the American Bar Association and the Estate Planning Council of America provide a wealth of information on estate planning best practices, legal requirements, and current trends in the field. By utilizing these resources, individuals can make informed decisions and create effective estate plans to secure their legacy for future generations.